$1,000–$1,249 tier
What car insurance costs in New Mexico
New Mexico's average premium against the national one, why uninsured motorist coverage deserves a hard look here, and where a driver can save.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,082
- Change from 2022
- +13%
- Minimum liability limits
- 25/50/10
- Uninsured drivers, 2023
- 24.1%
Bottom line
New Mexico drivers spent an average of $1,082 per insured car in 2023, about 16% below the national $1,282, and full coverage averaged $1,301. The state requires 25/50/10 liability, and every policy includes uninsured and underinsured motorist coverage unless you reject it. That matters here: the Insurance Research Council estimates 24.1% of New Mexico drivers were uninsured in 2023, the second-highest share in its state estimates.
The New Mexico bill, line by line
Guardbrook
Average car insurance bill, 2023
New Mexico
Liability$624
Collision$418
Comprehensive$259
Full coverage$1,301
Average spend per car$1,082
Compared with the U.S.−16%
Uninsured drivers24.1%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
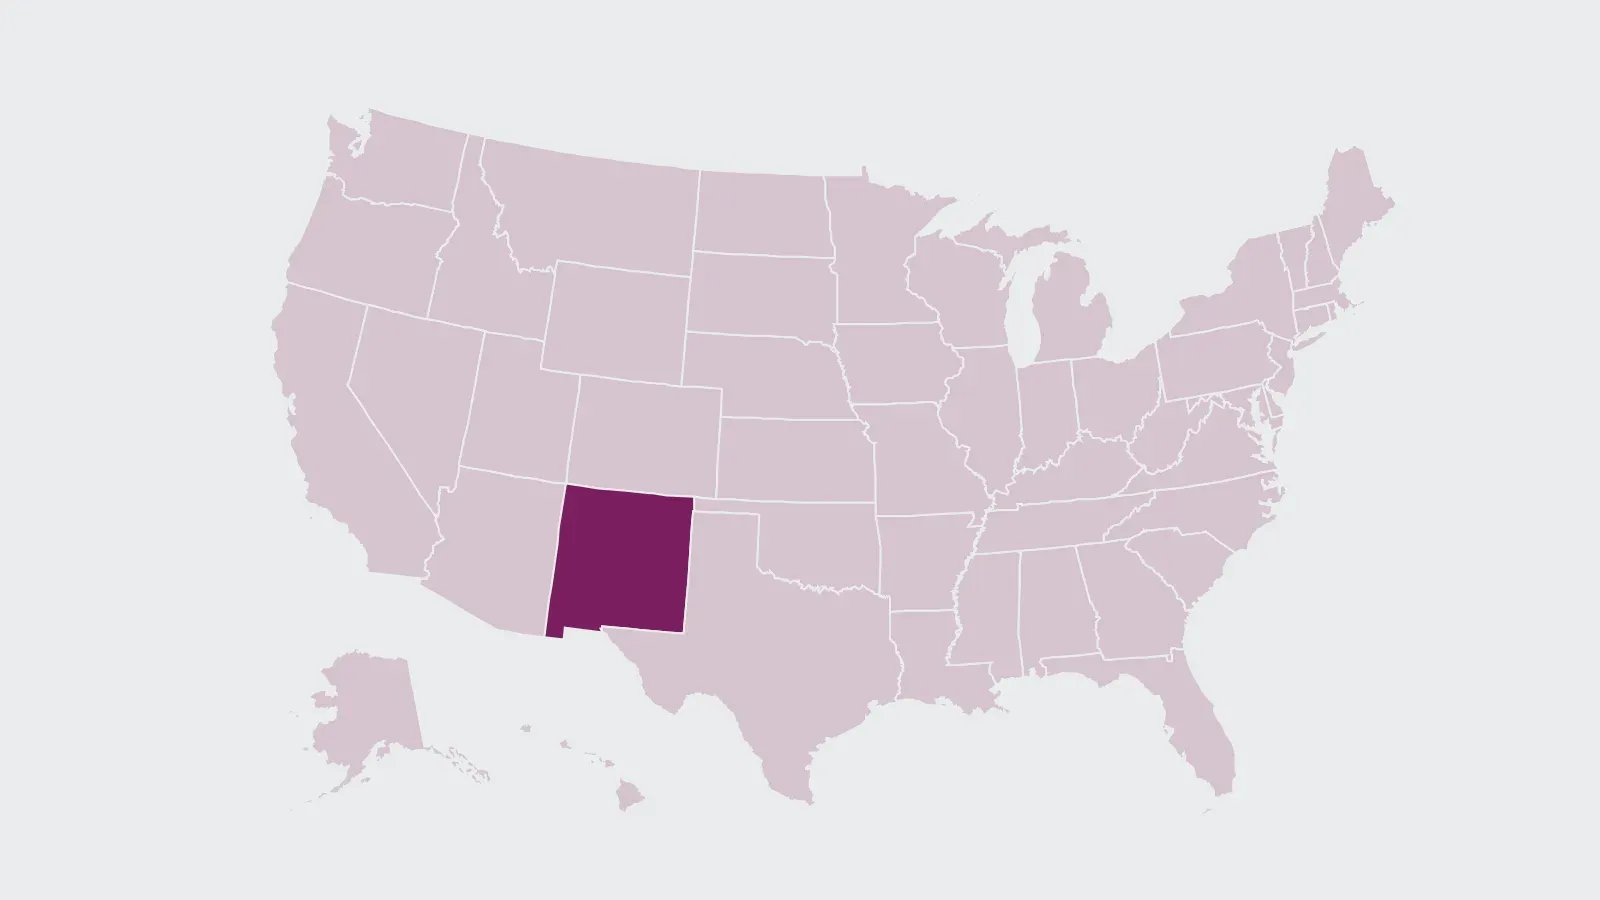
Price tier on the map
$1,000 to $1,249 a year
- Minimum liability limits
- 25/50/10
- UM/UIM included unless rejected (NMSA 66-5-301); $250 deductible on uninsured motorist property damage
- Credit-based insurance scores
- Allowed
- Office of Superintendent of Insurance consumer guidance
- Regulator
- New Mexico Office of Superintendent of Insurance
How New Mexico's bill compares
Each year the National Association of Insurance Commissioners (NAIC) totals the premiums insurers report by state. For 2023 New Mexico's average expenditure was $1,082 per insured car, 13% above the $958 of 2022. Expenditure counts liability-only and fully covered cars together; for a car with liability, collision and comprehensive, the combined premium averaged $1,301.
| Coverage | New Mexico | United States |
|---|---|---|
| Liability | $624 | $737 |
| Collision | $418 | $464 |
| Comprehensive | $259 | $238 |
| All three (combined premium) | $1,301 | $1,438 |
| Average expenditure | $1,082 | $1,282 |
Liability averaged about 15% below the national figure and collision about 10% below. Comprehensive, which pays for theft, glass, weather and other non-crash damage, ran about 9% above. The combined premium for full coverage ended up roughly 10% under the U.S. number. Your own quote will turn on your vehicle, record and ZIP code; see how location affects a premium.
Coverage New Mexico law requires
New Mexico requires every vehicle owner to carry insurance or other evidence of financial responsibility. Section 66-5-208 of the New Mexico Statutes sets the amounts: $25,000 for injury or death of one person, $50,000 for two or more people in one accident and $10,000 for property damage, or 25/50/10. A surety bond or cash deposit used instead must total $60,000.
- Uninsured and underinsured motorist coverage comes with every policy written for a car registered or garaged in New Mexico under Section 66-5-301. You may reject it, and you may buy it up to your own liability limits.
- Property damage from an uninsured driver can carry a deductible: the statute lets insurers exclude the first $250, which the Office of Superintendent of Insurance describes as a $250 deductible.
- Collision and comprehensive are optional under state law; a lender may insist on them.
A $10,000 property damage limit buys little against a late-model car, and with roughly one driver in four uninsured, the coverage that protects you from them is the line to think hardest about before rejecting. Our page on limits and deductibles walks through how much each step up costs and covers.
Credit and the price of a New Mexico policy
The Office of Superintendent of Insurance (OSI) tells consumers that insurers may use credit scores when setting premiums: a higher score can lower the price and a lower one can raise it. Companies weigh credit differently, which is one reason quotes for the same driver can differ. Read how credit-based insurance scores work before you shop, and check your credit reports for errors.
OSI's consumer guidance also lists discounts insurers may offer: bundling home and auto, insuring more than one vehicle, airbags and anti-lock brakes, membership in certain organizations, and a defensive driving course, which it flags as especially relevant for drivers 55 and older. These are offered at each company's discretion.
Coverage for drivers insurers turn away
The New Mexico Motor Vehicle Insurance Plan was created for eligible drivers who seek coverage and can't get it in the voluntary market. A licensed agent can tell you whether you qualify. Our guide to assigned risk plans covers how the application works and how to return to a regular insurer once your record improves.
Ways to bring a New Mexico premium down
- Compare at least three quotes on the same limits and deductibles, using our checklist for comparing quotes line by line.
- Ask for each discount OSI lists, and if you are 55 or older, ask whether a defensive driving course would lower your rate.
- Price uninsured motorist coverage instead of rejecting it by reflex. Ask what it adds to the premium at your liability limits.
- Bring disputes to OSI. You can dispute a cancellation or non-renewal with the Office of Superintendent of Insurance and file complaints through its website.
Questions drivers ask
What is the minimum car insurance in New Mexico?
Liability of 25/50/10: $25,000 per person and $50,000 per accident for injuries, and $10,000 for property damage. Uninsured and underinsured motorist coverage is included unless you reject it.
How many New Mexico drivers are uninsured?
The Insurance Research Council estimated 24.1% in 2023, against 15.4% nationally; only Mississippi's estimate was higher.
Is car insurance cheaper in New Mexico than the national average?
On average, yes. NAIC data for 2023 put New Mexico at $1,082 per insured car against $1,282 for the U.S., though comprehensive coverage cost slightly more than average.
Can New Mexico insurers use my credit score?
Yes. The Office of Superintendent of Insurance says insurers may use credit scores in setting premiums, so a lower score can mean a higher price.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- New Mexico Office of Superintendent of Insurance — Insurance tip of the month: auto insurance
- New Mexico Statutes § 66-5-208 — Evidence of financial responsibility; amounts (Justia, 2025)
- New Mexico Statutes § 66-5-301 — Uninsured and unknown motorists; rejection (Justia, 2025)
- AIPSO — New Mexico Motor Vehicle Insurance Plan
- New Mexico Office of Superintendent of Insurance
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state; the minimum limits were confirmed in the 2025 statutes.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Coverage limits and deductibles
What 25/50/25 means, why liability is about half of a $1,438 full-coverage bill, and how to size a deductible.
-
Shopping guide
Comparing quotes line by line
Match limits, deductibles and add-ons, list every driver, compare totals with fees, then check the company.
-
Price factor
Credit-based insurance scores
Allowed in most states, barred from auto rates in CA, HI, MA and MI. Your rights when credit raises the price.