Under $1,000 tier
What car insurance costs in Maine
Maine's average premium measured against the U.S., the higher limits the state requires, and the rules that help a Maine driver pay less.
By Guardbrook Editorial Team Updated 5 min read
At a glance
- Average yearly spend, 2023
- $856
- Change from 2022
- +12%
- Minimum liability limits
- 50/100/25
- Uninsured drivers, 2023
- 5.7%
Bottom line
Maine drivers spent an average of $856 per insured car in 2023, about 33% below the U.S. average of $1,282, and a car with all three main coverages averaged $926. That is despite one of the higher legal minimums: 50/100/25 liability, $2,000 of medical payments coverage and 50/100 uninsured motorist coverage. Maine also had the lowest estimated share of uninsured drivers in the country in 2023, 5.7%. Drivers 55 and older can get a discount required by state law after an approved course.
The Maine bill, line by line
Guardbrook
Average car insurance bill, 2023
Maine
Liability$425
Collision$336
Comprehensive$165
Full coverage$926
Average spend per car$856
Compared with the U.S.−33%
Uninsured drivers5.7%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
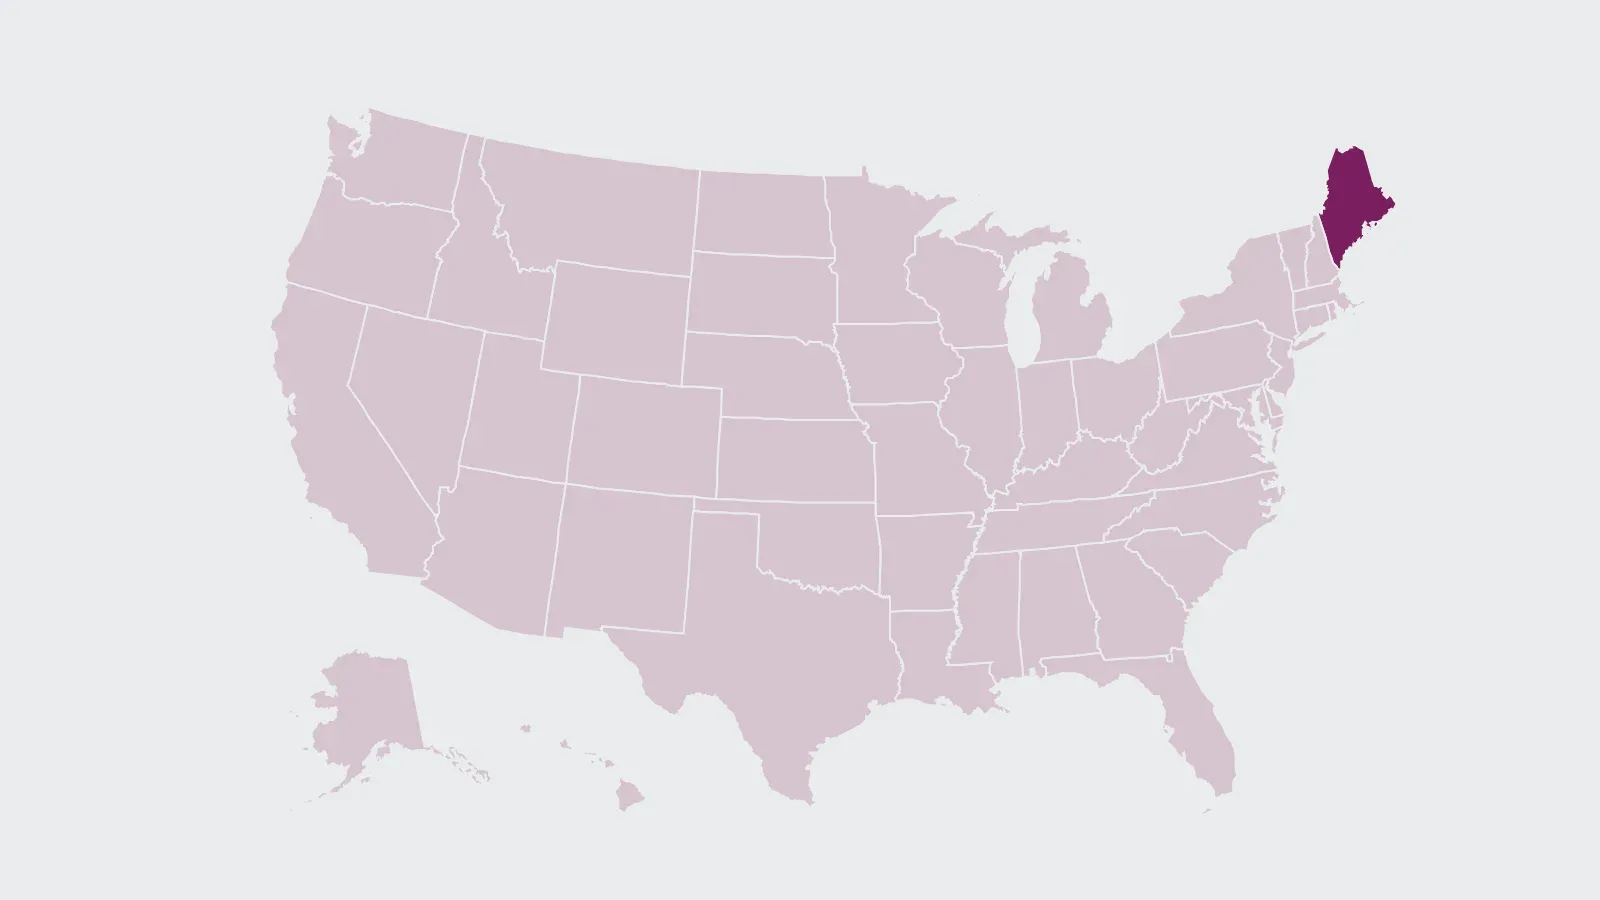
Price tier on the map
Under $1,000 a year
- Minimum liability limits
- 50/100/25
- Plus $2,000 medical payments and 50/100 uninsured/underinsured motorist coverage
- Credit-based insurance scores
- Allowed, not as the only factor
- 24-A M.R.S. §2169-B; re-scoring on request once every 12 months
- Regulator
- Maine Bureau of Insurance
Maine's bill beside the U.S. average
The National Association of Insurance Commissioners (NAIC) gathers the premiums insurers charge in every state. Its 2023 figures, the newest by state, put Maine's average expenditure at $856 per insured car, 12% more than the $767 of 2022. Since expenditure counts liability-only cars too, the NAIC also reports the combined premium for a car with liability, collision and comprehensive: $926 in Maine.
| Coverage | Maine | United States |
|---|---|---|
| Liability | $425 | $737 |
| Collision | $336 | $464 |
| Comprehensive | $165 | $238 |
| All three (combined premium) | $926 | $1,438 |
| Average expenditure | $856 | $1,282 |
Maine comes in below the national figure on every line. Liability, at $425, is about 42% lower even though Maine's minimum limits are twice the common 25/50 bodily injury level. Collision and comprehensive are each roughly 30% below the U.S. averages. These are averages across the state, and a driver's own record still moves the price most; see how a driving record counts.
The coverage Maine requires
Maine law (29-A M.R.S. §1605) sets the minimum at $50,000 per injured person and $100,000 per accident for bodily injury, $25,000 for property damage, and $2,000 of medical payments coverage. The Maine Bureau of Insurance adds that a $125,000 combined single limit also meets the liability requirement, and that proof of insurance is needed to register a vehicle.
- Medical payments of at least $2,000 per person cover the driver and passengers. The Bureau notes that $5,000, $10,000, $25,000 or more is available for a relatively small added cost.
- Uninsured/underinsured motorist coverage is required at a minimum of $50,000 per person and $100,000 per accident.
- Matching limits: if you buy liability above the minimum, your uninsured motorist limit must match it unless you reject the higher limit in writing.
The Bureau calls the minimums a starting point that may not fully protect your assets. Raising liability also raises the matched uninsured motorist limit, so price both together; our page on limits and deductibles shows how to weigh them.
How Maine handles rates and credit
Insurers set their own premiums, but the Bureau of Insurance reviews every auto rate filing and can object to rates that are excessive, inadequate or unfairly discriminatory. Under 24-A M.R.S. §2304-A, a company files a rate at least 30 days before its effective date, and an insurer must charge its current filed and approved rates, even if an agent quoted less.
Maine allows credit-based insurance scores within limits set by 24-A M.R.S. §2169-B. An insurer can't deny, cancel or refuse to renew a policy, or set a renewal rate, based only on credit, and its score can't factor in income, address, ZIP code, marital status, race or sex. If credit leads to a worse outcome, the notice must give up to four specific reasons. Once every 12 months you can ask the insurer to re-run your credit and re-rate the policy. More on credit-based insurance scores.
The Maine Automobile Insurance Plan
If no company will write your policy, often because of a poor driving record, you may qualify for the Maine Automobile Insurance Plan. It provides the state-required minimum coverage plus optional physical damage coverage. You apply through a producer certified by the plan and must certify that you tried to buy insurance in Maine in the previous 60 days. See our guide to assigned-risk plans.
Paying less for Maine car insurance
- Take the mature-driver course at 55 or older. Maine requires every auto insurer to discount liability, medical payments and collision coverage for drivers who complete an approved accident prevention course. It lasts 36 months, needs a new course every three years and isn't available if you or a household member had an at-fault accident, a moving violation or a suspension in the past three years.
- Ask for the discounts insurers commonly offer. The Bureau lists multi-car, good student, safety devices, anti-theft devices, low mileage, claim-free renewal and auto-home packages.
- Shop around before renewal. Get quotes on the same limits, then switch without a gap if another insurer is cheaper.
- Ask the Bureau for help. File a complaint online, or call 800-300-5000 or 207-624-8475 for help with the process.
Questions drivers ask
Why is Maine's car insurance cheaper than average if the minimums are high?
The NAIC data show the result, not the cause: Maine's 2023 average expenditure was $856 per insured car against $1,282 nationally, and liability averaged $425 against $737, even with 50/100/25 minimum limits.
What coverage is required in Maine?
Liability of 50/100/25 (or a $125,000 combined single limit), at least $2,000 of medical payments coverage, and uninsured/underinsured motorist coverage of at least $50,000/$100,000.
Do Maine insurers have to discount a senior driving course?
Yes. Drivers 55 and older who complete an approved accident prevention course get a required discount on liability, medical payments and collision coverage for 36 months. See course discounts.
Can a Maine insurer drop me because of my credit?
Not on credit alone. Maine law bars denying, canceling or refusing to renew a personal auto policy based solely on credit information.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Maine Bureau of Insurance — Insurance required by law
- Maine Bureau of Insurance — Auto insurance discounts
- Maine Bureau of Insurance — Auto insurance FAQs
- Maine Bureau of Insurance — File a complaint or dispute
- 29-A M.R.S. §1605 — Motor vehicle liability insurance minimums
- 24-A M.R.S. §2169-B — Use of consumer reports in insurance underwriting
- 24-A M.R.S. §2304-A — Rate filings
- AIPSO — Maine Automobile Insurance Plan
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Annual mileage
One of three rating factors named in California law, and a common discount elsewhere. How miles are checked.
-
Way to save
Telematics and usage-based insurance
What tracking apps and plug-ins record, whether your price can rise, and 5 privacy questions to ask first.
-
Shopping guide
Switching insurers without a gap
Start the new policy first, cancel in writing, tell the lender. A North Carolina lapse can cost up to $200 in fees.