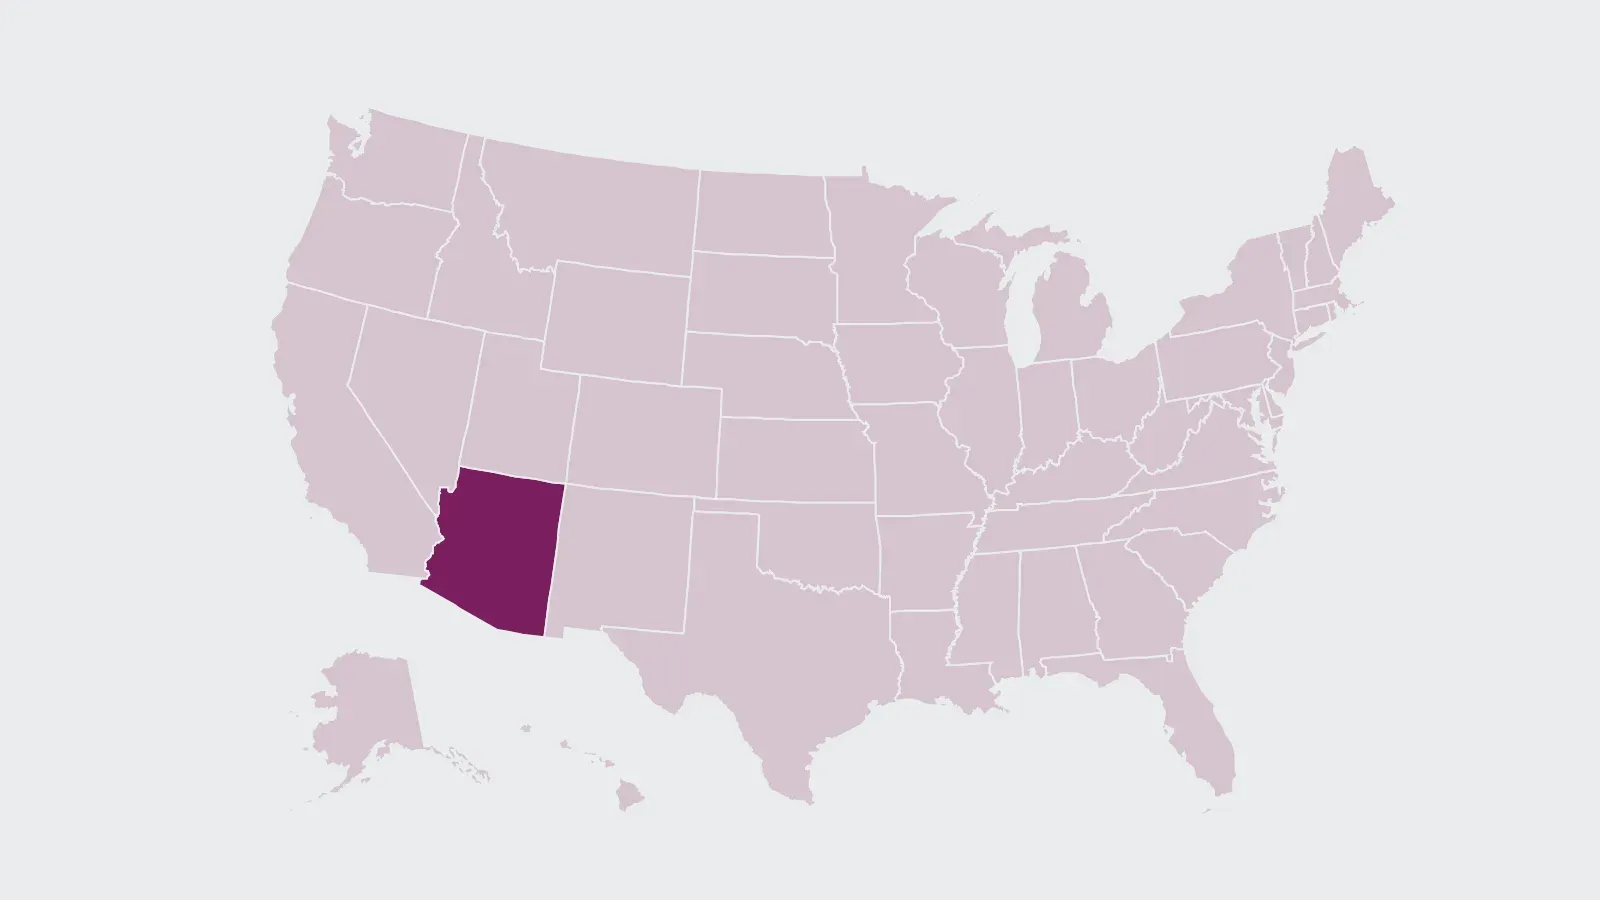
$1,250–$1,499 tier
What car insurance costs in Arizona
Arizona's average premium set against the U.S. figures, the coverage the state requires, how credit can be used, and the steps that can lower your bill.
By Guardbrook Editorial Team Updated 5 min read
At a glance
- Average yearly spend, 2023
- $1,344
- Change from 2022
- +16%
- Minimum liability limits
- 25/50/15
- Uninsured drivers, 2023
- 10.6%
Bottom line
Arizona drivers spent an average of $1,344 per insured car in 2023, about 5% more than the U.S. average of $1,282, after a 16% jump from 2022. Full coverage averaged $1,504. The state's minimum is 25/50/15, and insurers must offer uninsured and underinsured motorist coverage in writing. Arizona lets insurers use credit history but bars several items from insurance scores, such as medical collections.
The Arizona bill, line by line
Guardbrook
Average car insurance bill, 2023
Arizona
Liability$793
Collision$436
Comprehensive$275
Full coverage$1,504
Average spend per car$1,344
Compared with the U.S.+5%
Uninsured drivers10.6%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
Price tier on the map
$1,250 to $1,499 a year
- Minimum liability limits
- 25/50/15
- Since July 1, 2020; UM/UIM must be offered in writing (A.R.S. § 20-259.01)
- Credit-based insurance scores
- Allowed, with limits
- A.R.S. § 20-2110 bars medical collections and other items from insurance scores
- Regulator
- Arizona Department of Insurance and Financial Institutions
Arizona's average premium in numbers
The National Association of Insurance Commissioners (NAIC) reports what insurers collected per insured car in each state. In 2023, its latest state data, the Arizona average expenditure was $1,344, up 16% from $1,155 in 2022. Expenditure includes liability-only cars; a car with liability, collision and comprehensive together had a combined premium of $1,504.
| Coverage | Arizona | United States |
|---|---|---|
| Liability | $793 | $737 |
| Collision | $436 | $464 |
| Comprehensive | $275 | $238 |
| All three (combined premium) | $1,504 | $1,438 |
| Average expenditure | $1,344 | $1,282 |
Liability, at $793, ran about 8% above the national figure, and comprehensive, at $275, about 16% above it. Collision came in a little below the U.S. average. The overall rise from 2022 (16%) was also faster than the national one (14%). Your quote depends on your own record, car and address; our page on how your driving record affects price explains one of the biggest levers.
Arizona's coverage requirements
Arizona's minimum liability is $25,000 for one person's injury or death, $50,000 for two or more people in one accident and $15,000 for damage to other people's property: 25/50/15. These limits apply to policies issued or renewed since July 1, 2020, under A.R.S. § 28-4009. The Arizona Department of Insurance and Financial Institutions (DIFI) notes that your premium may rise to reflect the higher coverage.
- Uninsured and underinsured motorist coverage must be offered to you in writing on a form approved by the director (A.R.S. § 20-259.01). Your declarations page records whether you bought or rejected it. The Insurance Research Council estimated 10.6% of Arizona drivers were uninsured in 2023.
- Collision, comprehensive and medical payments aren't part of the state minimum, though a lender will usually require physical damage coverage on a financed car.
If you buy uninsured motorist coverage, its limits can go as high as your bodily injury liability limits. Matching them costs more but protects you against a driver with too little insurance; see limits and deductibles for how to compare.
Credit and pricing in Arizona
Arizona allows insurers to use credit history but limits what goes into an insurance score (A.R.S. § 20-2110). Insurers may not count medical collection accounts, bankruptcies or satisfied liens more than seven years old, your total available line of credit, or the type of credit card you use unless it is actuarially justified. Income, gender, address, ZIP code, ethnic group, religion, marital status and nationality can't be used to calculate the score.
If an insurer takes adverse action based on your credit, it has to tell you the decision was based in part on a consumer report or the absence of credit history. Prices still vary a lot between companies; more on credit-based insurance scores.
Coverage when the market says no
A driver who can't get insurance from regular companies can apply to the Arizona Automobile Insurance Plan, the state's assigned-risk plan, administered by AIPSO. It serves applicants who can't obtain coverage in the voluntary market; its customer service line is (800) 227-4659. Rates are usually higher than in the regular market. Read our guide to assigned-risk plans before you apply.
Steps to a smaller Arizona premium
- Shop with identical limits. Ask two or three insurers to quote the same liability, uninsured motorist and deductible choices so the prices are comparable.
- Consider how you pay. Monthly plans can carry installment fees; the monthly vs. pay-in-full calculator shows the difference.
- Check your credit report. Because medical collections and old bankruptcies can't count in an Arizona insurance score, an error there is worth disputing.
- Complain if a company mishandles your policy. DIFI takes consumer complaints online and by phone at (602) 364-2499, weekdays 9 a.m. to 4 p.m.
Questions drivers ask
Is car insurance in Arizona more expensive than average?
Slightly. NAIC data for 2023 show an average Arizona expenditure of $1,344 per insured car against $1,282 nationally, and a full-coverage combined premium of $1,504 against $1,438.
What are Arizona's minimum car insurance limits?
25/50/15 for policies issued or renewed since July 1, 2020: $25,000 per person and $50,000 per accident for injuries, and $15,000 for property damage.
Do I have to buy uninsured motorist coverage in Arizona?
No, but insurers must offer uninsured and underinsured motorist coverage in writing, and your declarations page shows what you chose.
What credit information can't an Arizona insurer use?
Medical collection accounts, bankruptcies or satisfied liens older than seven years, and your total available line of credit, among others. See credit-based insurance scores.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Arizona DIFI — Minimum auto insurance coverage
- A.R.S. § 28-4009 — Motor vehicle liability insurance policy requirements
- A.R.S. § 20-259.01 — Uninsured and underinsured motorist coverage
- A.R.S. § 20-2110 — Use of credit information by insurers
- Arizona DIFI — Filing a complaint
- AIPSO — Arizona Automobile Insurance Plan
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Driving record
Tickets and at-fault crashes raise prices; OR and MD look back 3 years, CA Good Driver rates are 20%+ lower.
-
Way to save
Paying in full vs. monthly
A $1,200 premium can cost $45 more by the month, about 17.8% as an APR. When monthly still makes sense.
-
Shopping guide
Comparing quotes line by line
Match limits, deductibles and add-ons, list every driver, compare totals with fees, then check the company.