$1,250–$1,499 tier
What car insurance costs in South Carolina
South Carolina's average premium beside the national figure, the coverage state law builds into every policy, and how rate changes reach your bill.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,367
- Change from 2022
- +13%
- Minimum liability limits
- 25/50/25
- Uninsured drivers, 2023
- 10.3%
Bottom line
South Carolina drivers spent an average of $1,367 per insured car in 2023, about 7% above the U.S. average of $1,282; full coverage averaged $1,517. The liability line explains the gap. State law requires 25/50/25 liability plus uninsured motorist coverage at the same limits. Insurers can change overall rates by up to 7% without approval in advance; larger changes need the regulator's approval first.
The South Carolina bill, line by line
Guardbrook
Average car insurance bill, 2023
South Carolina
Liability$879
Collision$386
Comprehensive$251
Full coverage$1,517
Average spend per car$1,367
Compared with the U.S.+7%
Uninsured drivers10.3%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
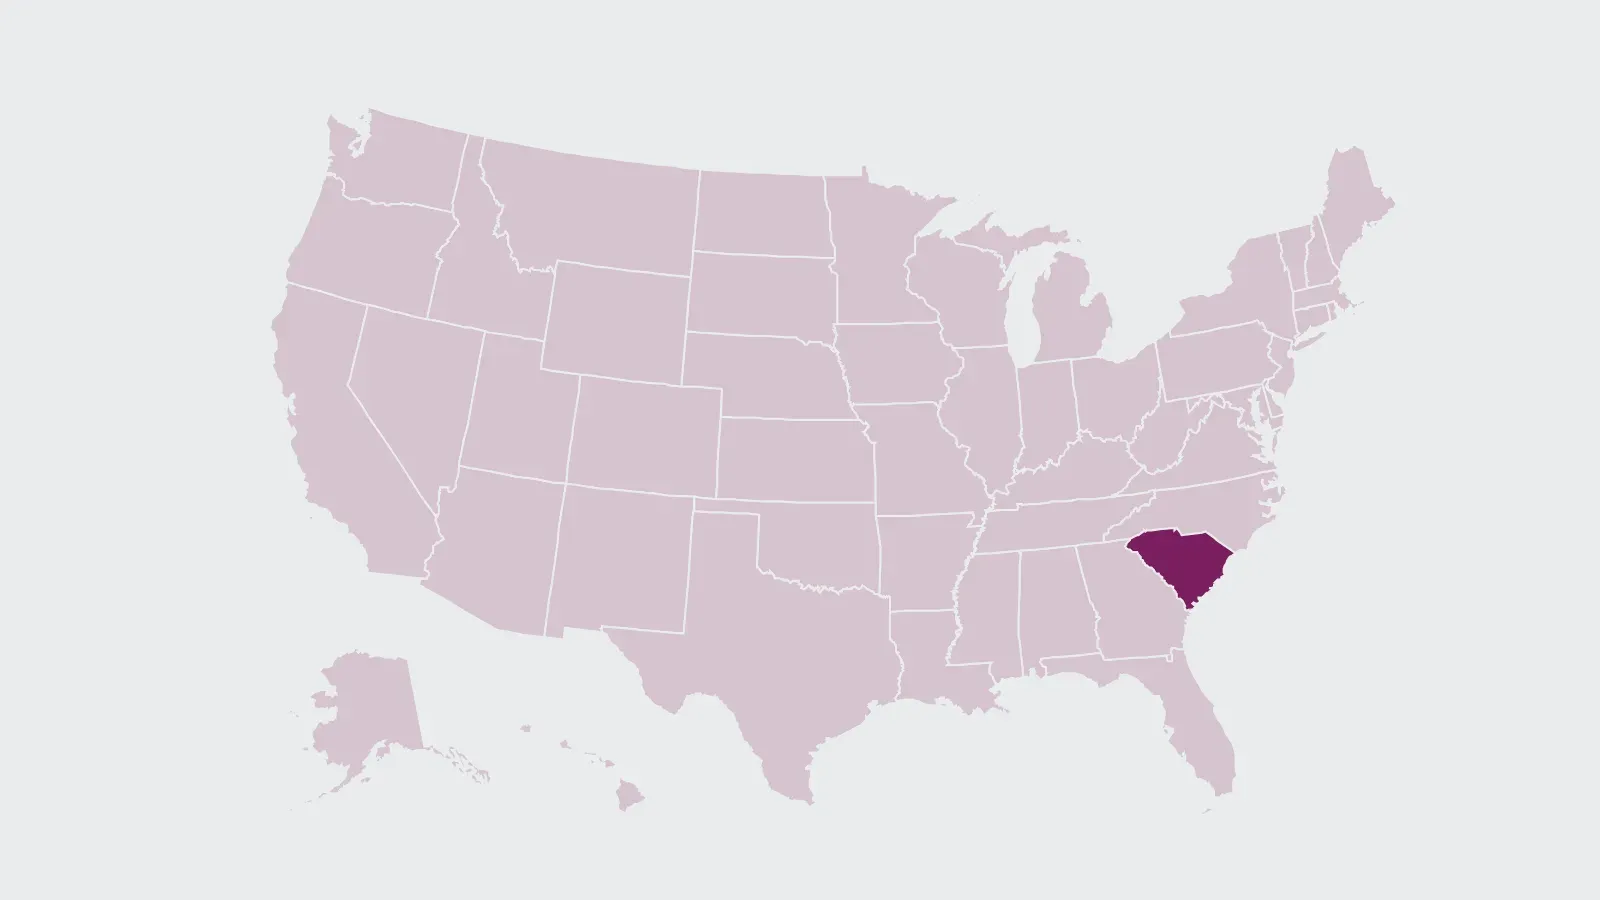
Price tier on the map
$1,250 to $1,499 a year
- Minimum liability limits
- 25/50/25
- Uninsured motorist coverage required at the same limits (S.C. Code § 38-77-150); UIM must be offered
- Credit-based insurance scores
- Allowed
- S.C. Code § 38-73-740: credit reports used for auto rating kept on file 3 years, open to the applicant
- Regulator
- South Carolina Department of Insurance
South Carolina's bill against the U.S.
The National Association of Insurance Commissioners (NAIC) collects what insurers charge per insured car in every state. Its 2023 figures, the most recent by state, put South Carolina's average expenditure at $1,367, up 13% from $1,205 in 2022. That number blends cars with liability only and cars with full coverage. A car insured for liability, collision and comprehensive cost $1,517 on average.
| Coverage | South Carolina | United States |
|---|---|---|
| Liability | $879 | $737 |
| Collision | $386 | $464 |
| Comprehensive | $251 | $238 |
| All three (combined premium) | $1,517 | $1,438 |
| Average expenditure | $1,367 | $1,282 |
Liability ran $142 above the national average, while collision was $78 below it and comprehensive about $13 above. In other words, the extra cost sits in the coverage that protects other people, which every South Carolina driver has to carry. Your driving record is one of the main inputs into that line; see how tickets and accidents raise a premium.
Coverage South Carolina builds in
South Carolina Code § 38-77-140 sets the liability floor at $25,000 for injury to one person, $50,000 for injuries to two or more people in one accident and $25,000 for property damage. Insurers may write higher limits, and you can ask for them on any quote.
- Uninsured motorist coverage is mandatory. Under § 38-77-150, every policy must include it at limits no lower than the liability minimums, including at least $25,000 for property damage, though the first $200 of a property loss may be excluded.
- Higher limits and underinsured motorist coverage must be offered to you, up to your liability limits, under § 38-77-160. They are optional.
- Collision and comprehensive aren't required by the state, but a lender or leasing company will usually require them.
The Insurance Research Council estimates that 10.3% of South Carolina drivers were uninsured in 2023, below the U.S. rate of 15.4%. Underinsured motorist coverage, which pays when the at-fault driver's limits run out, is the optional piece worth pricing. Our page on limits and deductibles covers the trade-off.
How rate changes are approved
South Carolina uses a band. Under § 38-73-905, an insurer can raise or lower its overall average rate level for car insurance, all coverages combined, by up to 7% on a file-and-use basis, without prior approval, and no more than twice in any 12 months. Any other increase is subject to prior approval by the director of the Department of Insurance.
That doesn't cap your own bill: a rate level is an average, and your premium can still move with a new car, a claim or a change in your household. If your renewal jumps, our guide to why a premium goes up lists the questions to ask.
On credit, state law (§ 38-73-740) says that when an insurer uses a credit report to set an auto applicant's classification or premium, it must keep the report on file for at least three years and let the applicant inspect it on request. More on credit-based insurance scores.
High-risk drivers and group policies
A driver who is legally entitled to car insurance but can't get a liability policy can turn to the Associated Auto Insurers Plan, the residual market set up in Chapter 77 of Title 38. Applicants can ask the director of the Department of Insurance to have their risk assigned to an insurer. Ask for regular quotes again as tickets and accidents age off your record.
State law also gives groups a price break: under § 38-77-130, a group auto policy written for a group of 20 or more must carry a rate at least 5% below the individual rate for a substantially similar policy. If your employer or an association offers group auto coverage, ask whether it is written this way; see group and affinity discounts.
Lowering a South Carolina premium
- Get quotes from two or three companies on the same liability, uninsured and underinsured limits, since the liability line is where South Carolina prices run high.
- Look at your deductibles. Collision averaged less here than nationally. Before raising the deductible, check the trade-off with the deductible break-even calculator.
- Ask about group coverage through an employer, union or association, and whether the state's 5% group rule applies.
- Take a dispute to the South Carolina Department of Insurance if your insurer won't resolve it.
Questions drivers ask
Is car insurance more expensive in South Carolina than the national average?
Yes, by about 7% in NAIC's 2023 data: $1,367 per insured car against $1,282. Liability was $879 against $737 nationally; collision was lower.
What car insurance is required in South Carolina?
Liability of 25/50/25 and uninsured motorist coverage at no less than the same limits, including $25,000 for property damage. Underinsured motorist coverage must be offered but is optional.
Do South Carolina insurers need approval to raise rates?
Overall rate level changes of up to 7% can take effect on a file-and-use basis, no more than twice in 12 months. Larger increases need prior approval from the director of the Department of Insurance.
Can I see the credit report my insurer used?
South Carolina law requires an insurer that uses a credit report to set an auto applicant's classification or premium to keep it on file for three years and make it available for the applicant to inspect on request.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- South Carolina Code, Title 38, Chapter 77 — Automobile insurance (§§ 38-77-10, 38-77-130, 38-77-140, 38-77-150, 38-77-160)
- South Carolina Code, Title 38, Chapter 73 — Rates and rating (§§ 38-73-740, 38-73-905)
- U.S. Bureau of Labor Statistics — CPI, table 2 (motor vehicle insurance)
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Driving record
Tickets and at-fault crashes raise prices; OR and MD look back 3 years, CA Good Driver rates are 20%+ lower.
-
Shopping guide
Why your premium went up
Market-wide changes vs. your own record. The price index fell 5.0% to September 2026; yours may not have.
-
Way to save
Group and affinity discounts
South Carolina group policies must cost at least 5% less; Louisiana gives service members 25% off liability.